

Massimo Fabozzi, FAMA Broker sponsor of Milano è FORTE dei Marmi: Risk Management for businesses, assets and collector cars
From insurance portfolio analysis to Risk Management and Business Continuity: Massimo Fabozzi's approach puts the prevention and protection of businesses, professionals, individuals and assets at its core.
In a world where risks are becoming increasingly complex, being insured does not necessarily mean being adequately protected.
It is this principle that underpins the professional approach of Massimo Fabozzi, owner of FAMA Broker, a firm specializing in insurance consulting and brokerage.
The difference is fundamental: the starting point is not the policy to sell, but the risk to understand.
Before identifying insurance coverage, it is necessary to understand the client's needs, review existing protections, identify any vulnerabilities, and assess the financial and operational consequences that could result from an unforeseen event.
A philosophy that turns the broker from a mere insurance intermediary into a risk management consultant.
Massimo Fabozzi: analyze before insuring
At the heart of the model developed by FAMA Broker are the Insurance Portfolio Check and Risk Management.
The work begins with a detailed analysis of the insurance contracts already taken out by the client.
The aim is to verify whether the coverage is truly adequate in light of the potential risks to which a company, a professional or an individual may be exposed.
The process therefore goes beyond checking whether a policy exists.
FAMA Broker analyzes the features of the insurance products taken out, the quality of the service provided and whether premiums are commensurate with the value and terms of the coverage.
The outcome may be confirmation of the existing solutions or, when necessary, their revision or a search for alternatives when they next come up for renewal
FAMA BROKER services
FAMA Broker is a strategic insurance consultant specializing in the legal, asset and reputational protection of medical and scientific associations and their members.
FAMA Broker offers medical professional liability coverage at preferential rates for member physicians in line with the so-called Gelli-Bianco Law, also allowing them to take out insurance for civil and criminal defense in proceedings involving alleged gross negligence or malpractice. FAMA Broker continually adjusts insurance coverage by carefully identifying the risks to which professionals are exposed.
Insurance Portfolio Check: understanding how we are really protected
Over the years, businesses and individuals may accumulate numerous insurance policies.
The risk is ending up with overlapping coverage in some areas while, at the same time, leaving other exposures insufficiently covered.
Hence the importance of a comprehensive analysis.
The insurance portfolio check makes it possible to create a snapshot of the protections in place and compare it with the risks actually faced.
This is an apparently simple but crucial principle: before buying new coverage, it is necessary to understand what you already have and what is genuinely missing.
Risk Management: preventing risk before transferring it
The approach adopted by Massimo Fabozzi and FAMA Broker also extends to Risk Management.
The aim is to identify the areas of risk to which a company or an individual may be exposed and determine the most appropriate tools for limiting their consequences.
Insurance is only one of the possible responses.
Prevention comes even before transferring risk to an insurance company.
Analyzing vulnerabilities, reducing the likelihood of a particular event occurring, and putting appropriate procedures in place can be just as important as insuring against its financial consequences.
This is a modern approach to protection, in which prevention, management and insurance become parts of a single strategy.
Business Continuity: what happens to a company after a major event?
A fire. A flood. An earthquake. A major breakdown of a machine or facility.
For a company, the problem is not limited to physical damage.
The key question becomes: how long will it take for the business to return to normal operations?
This is where Business Continuity Management (BCM) comes into play.
FAMA Broker provides consulting for projects aimed at putting in place solutions, procedures and tools that can support the rapid and effective restoration of business processes following potentially disastrous events.
Business continuity is now a strategic element for many companies.
Because even when physical damage is covered by insurance, a prolonged interruption of business can have very significant financial, commercial and organizational consequences.
From Business Impact Analysis to Disaster Recovery Plan
Consulting can extend to the various components needed to build a structured business continuity strategy.
These include the Business Impact Analysis, the Business Continuity Plan, the Disaster Recovery Plan and Crisis Management.
Business Impact Analysis makes it possible to identify the processes that are most critical to the organization and assess the consequences of their interruption.
The Business Continuity Plan, by contrast, defines procedures and operating arrangements through which a company can continue or resume its essential activities.
Disaster Recovery specifically concerns the ability to restore infrastructure, systems and operations after a major event.
Crisis Management completes the picture, preparing the organization to handle emergency situations in a coordinated manner.
An approach for businesses, professionals and individuals
The concept of risk management is not limited exclusively to large companies.
Professionals, entrepreneurs and individuals may also have complex assets and insurance needs that call for specific analysis.
Real estate, professional activities, liabilities, valuable possessions and personal assets may present very different exposures.
This is precisely where customization becomes crucial.
There is no universally valid insurance solution: a solution must be designed around the specific risk the client faces.
Collector cars, supercars and automotive assets
For the OldCar24 audience, this approach also has particular significance in the automotive sector.
A classic car collection, a supercar or a high-value vehicle is not merely a means of transportation, but a genuine asset in its own right.
Value, storage location, use, transportation, participation in events, changes in market valuations and the specific characteristics of the vehicle are factors that can affect an accurate risk assessment.
A collection of cars may also be just one part of a much broader personal or business estate.
For this reason, protecting a vehicle can be incorporated into an overall assessment of the client's needs rather than considered in isolation.
The broker's role according to Massimo Fabozzi
The professional model developed by Massimo Fabozzi is therefore based on a clear view of brokerage.
A broker should not get involved only when it is time to take out a new policy.
The broker's role can begin much earlier, with an analysis of risks and existing coverage, and continue over time by monitoring how the client's needs evolve.
A company changes.
Wealth grows.
The value of assets can increase.
New risks emerge.
And protection that was adequate a few years ago may no longer be sufficient today.
Hence the importance of periodically reviewing insurance and risk management strategies.
FAMA Broker: from policy to protection strategy
FAMA Broker's philosophy can therefore be summed up in one fundamental principle:
do not start with insurance, but with an understanding of risk.
This means analyzing what could happen, understanding what the consequences would be, and deciding which risks to prevent, which to mitigate, and which to transfer through insurance.
For businesses, professionals and individuals with significant assets, this distinction can make all the difference.
And it is precisely this culture of prevention and informed risk management that Massimo Fabozzi and FAMA Broker have built their consulting model on.
Because insuring assets is important.
Truly understanding the risks they face is the first step toward protecting them.
Galleria immagini
Stefano Graidi: Great Wines and Classic Cars, the Italian Art of Collecting Emotions. Terre di Serrapetrona
Beauty, class, uniqueness and value that grows over time. There is a profound bond between the world of great wines and that of classic cars: two passions that tell the story of cu...
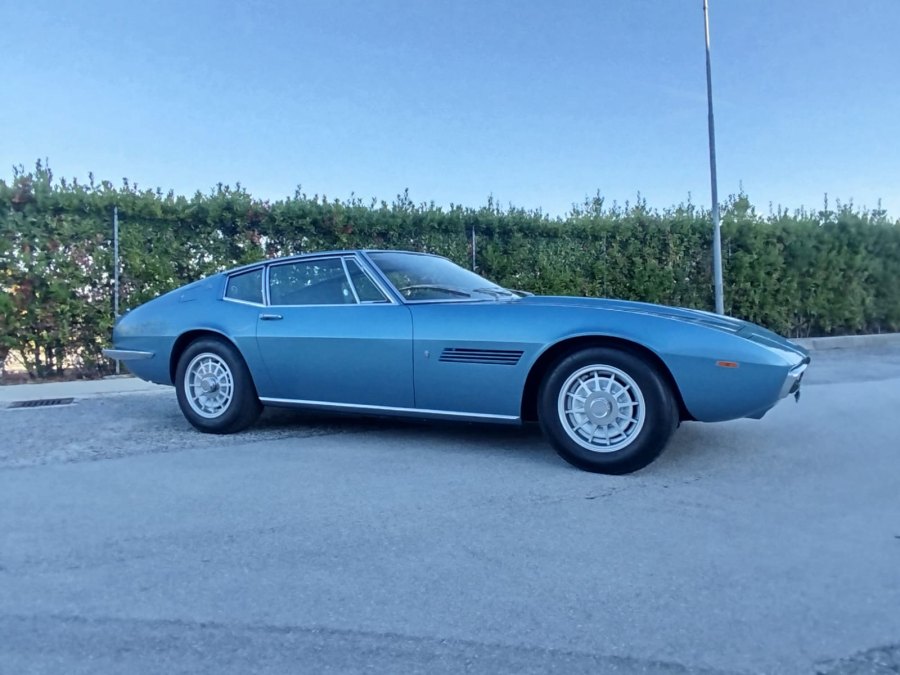
Maserati Ghibli: the star of the OldCar24 stand at Auto e Moto d’Epoca Bologna 2026
An example with a fascinating history, returned to its original configuration through a complete restoration costing around 200,000 euros.There are cars capable of crossing the era...
Milano Portofino Under the Stars 2026: the exclusive event for Gentleman Collectors, 7–8 November 2026
There are roads you travel. And then there are experiences that stay in your memory.On 7 and 8 November 2026, the Milano Portofino event returns, this time in an even more evocativ...
Dal network
In vetrina
Selezione premium · OldCar24